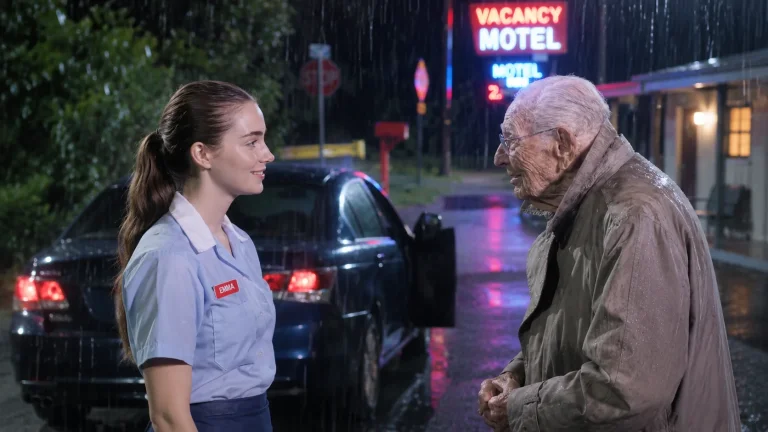
Nia told her that she had spent enough time being blamed for things she did not do.
She was not going to make the same mistake with somebody else.
Lena studied her for a moment and then apologized for approaching her unexpectedly.
Before leaving, she said that the eighty dollars had never been the real reason Nia was fired.
Nia asked what she meant.
Lena looked toward the street, where a dark sedan was slowing at the traffic light.
She said that somebody had needed a public example, and Nia’s emergency had given them one.
Then she walked to her car and drove away.
Nia remained beneath the awning until the sedan disappeared.
She could not tell whether the driver had been watching her or merely waiting for the light to change.
The distinction was becoming painfully familiar.
At Bellmont headquarters, an independent forensic accountant named Harold Finch was examining the first batch of preserved records.
Harold had spent twenty years investigating accounting irregularities, and he distrusted explanations that relied on one unusually dishonest employee.
Most sustained schemes, he knew, required weak controls, indifferent supervisors, or people who benefited from not asking questions.
The register logs showed that Nia’s drawer had been opened under a supervisor override while she was performing emergency assistance.
The override credential belonged to Gerald Voss.
That fact was important, but Harold refused to treat it as proof that Gerald had physically removed cash.
Credentials could be shared, misused, or stolen, and the audit trail needed to be tested against video and witness accounts.
Harold asked the technical team to preserve original log files, authentication records, and the device used to approve the override.
He also requested the company’s policy governing emergency interruptions at registers.
The policy required a supervisor to secure an unattended drawer when an employee left because of an emergency.
Gerald had cited a different policy when he fired Nia.
Harold made a note of the conflict.
He then compared the earlier shortage reports with a list of stores under Martin Keene’s regional supervision.
A pattern emerged that he did not like.
Several stores had experienced similar losses shortly before reducing staff or replacing long-serving cashiers with temporary workers.
The reported losses were then used to justify disciplinary terminations and to support claims that labor costs had been reduced through better management.
Those claims appeared in performance presentations sent to investors.
Harold followed the figures into a spreadsheet prepared for a regional incentive program.